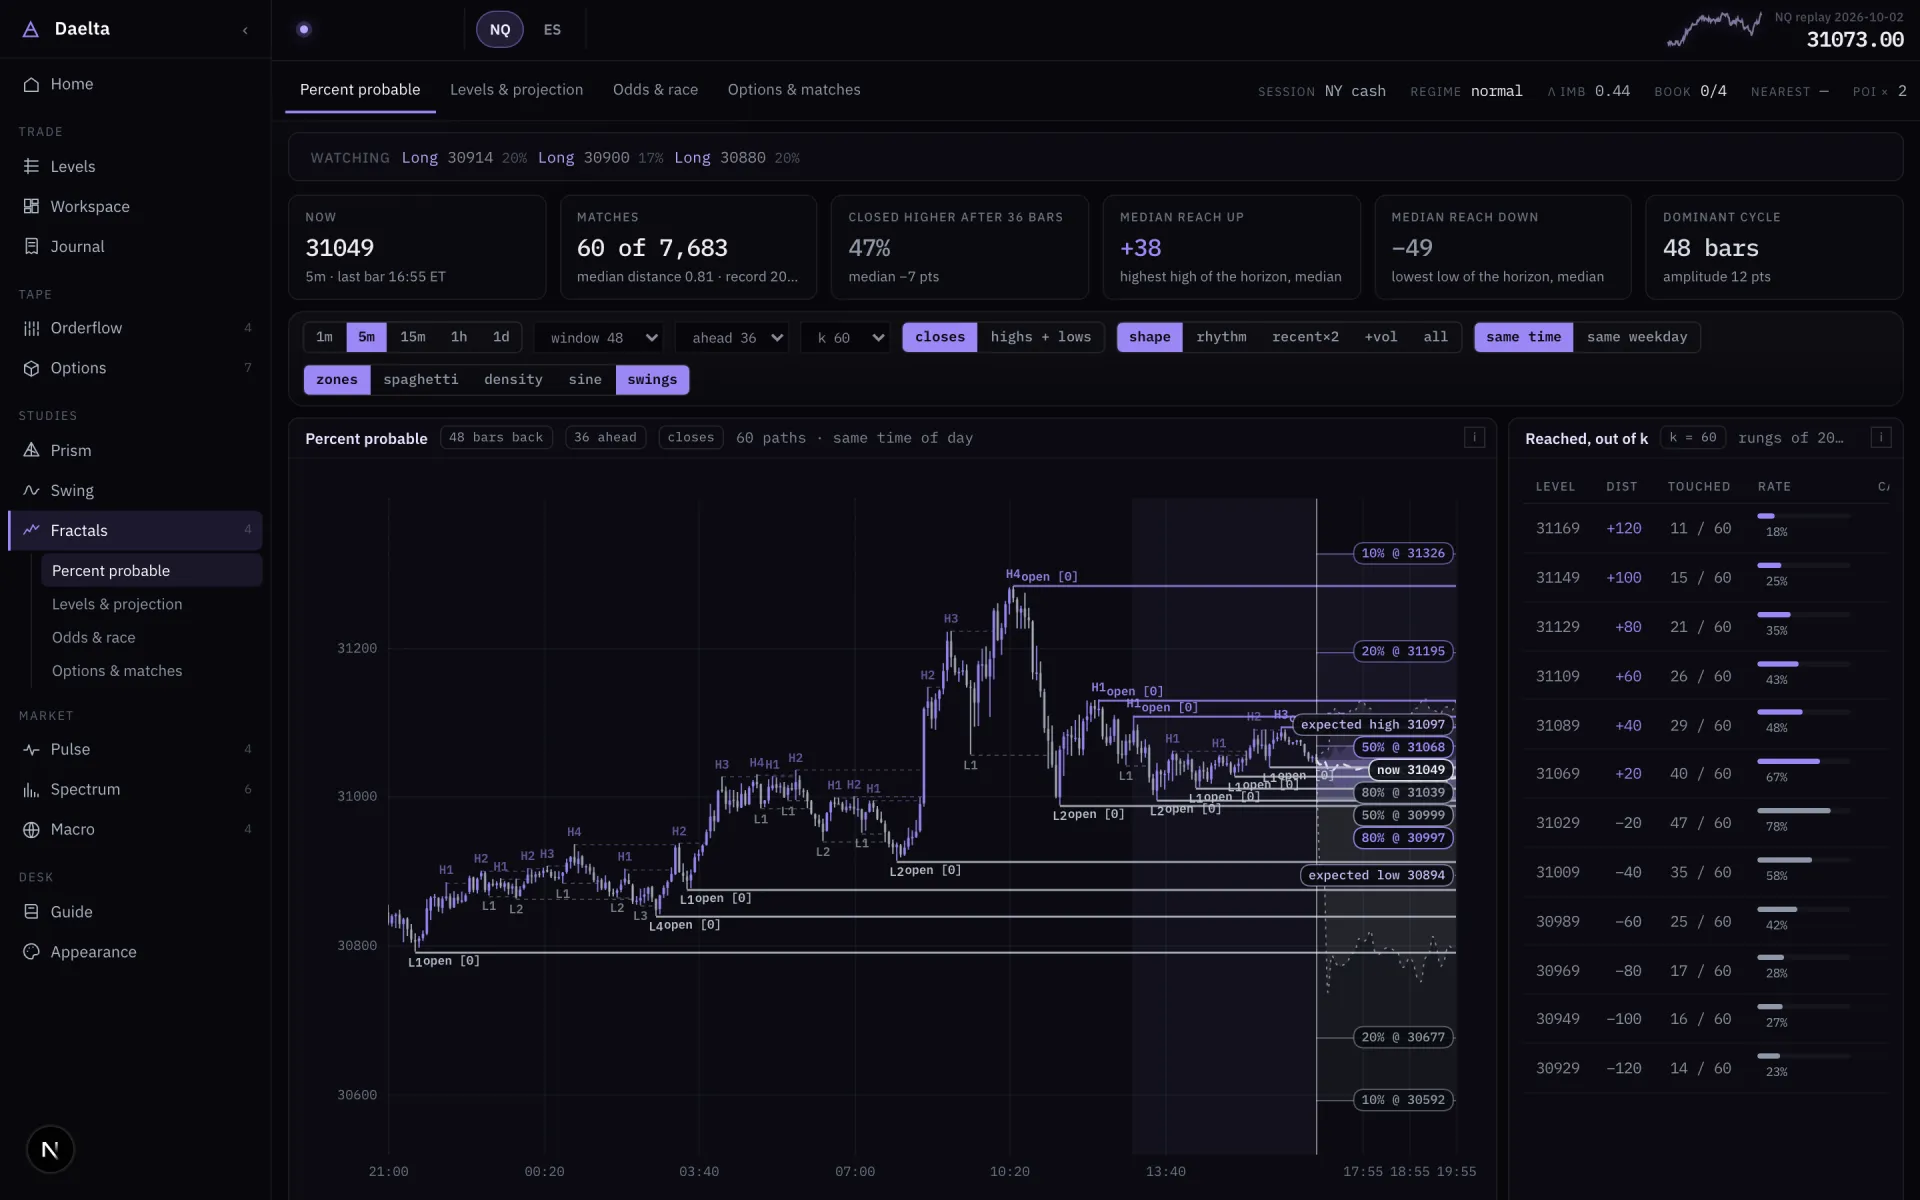
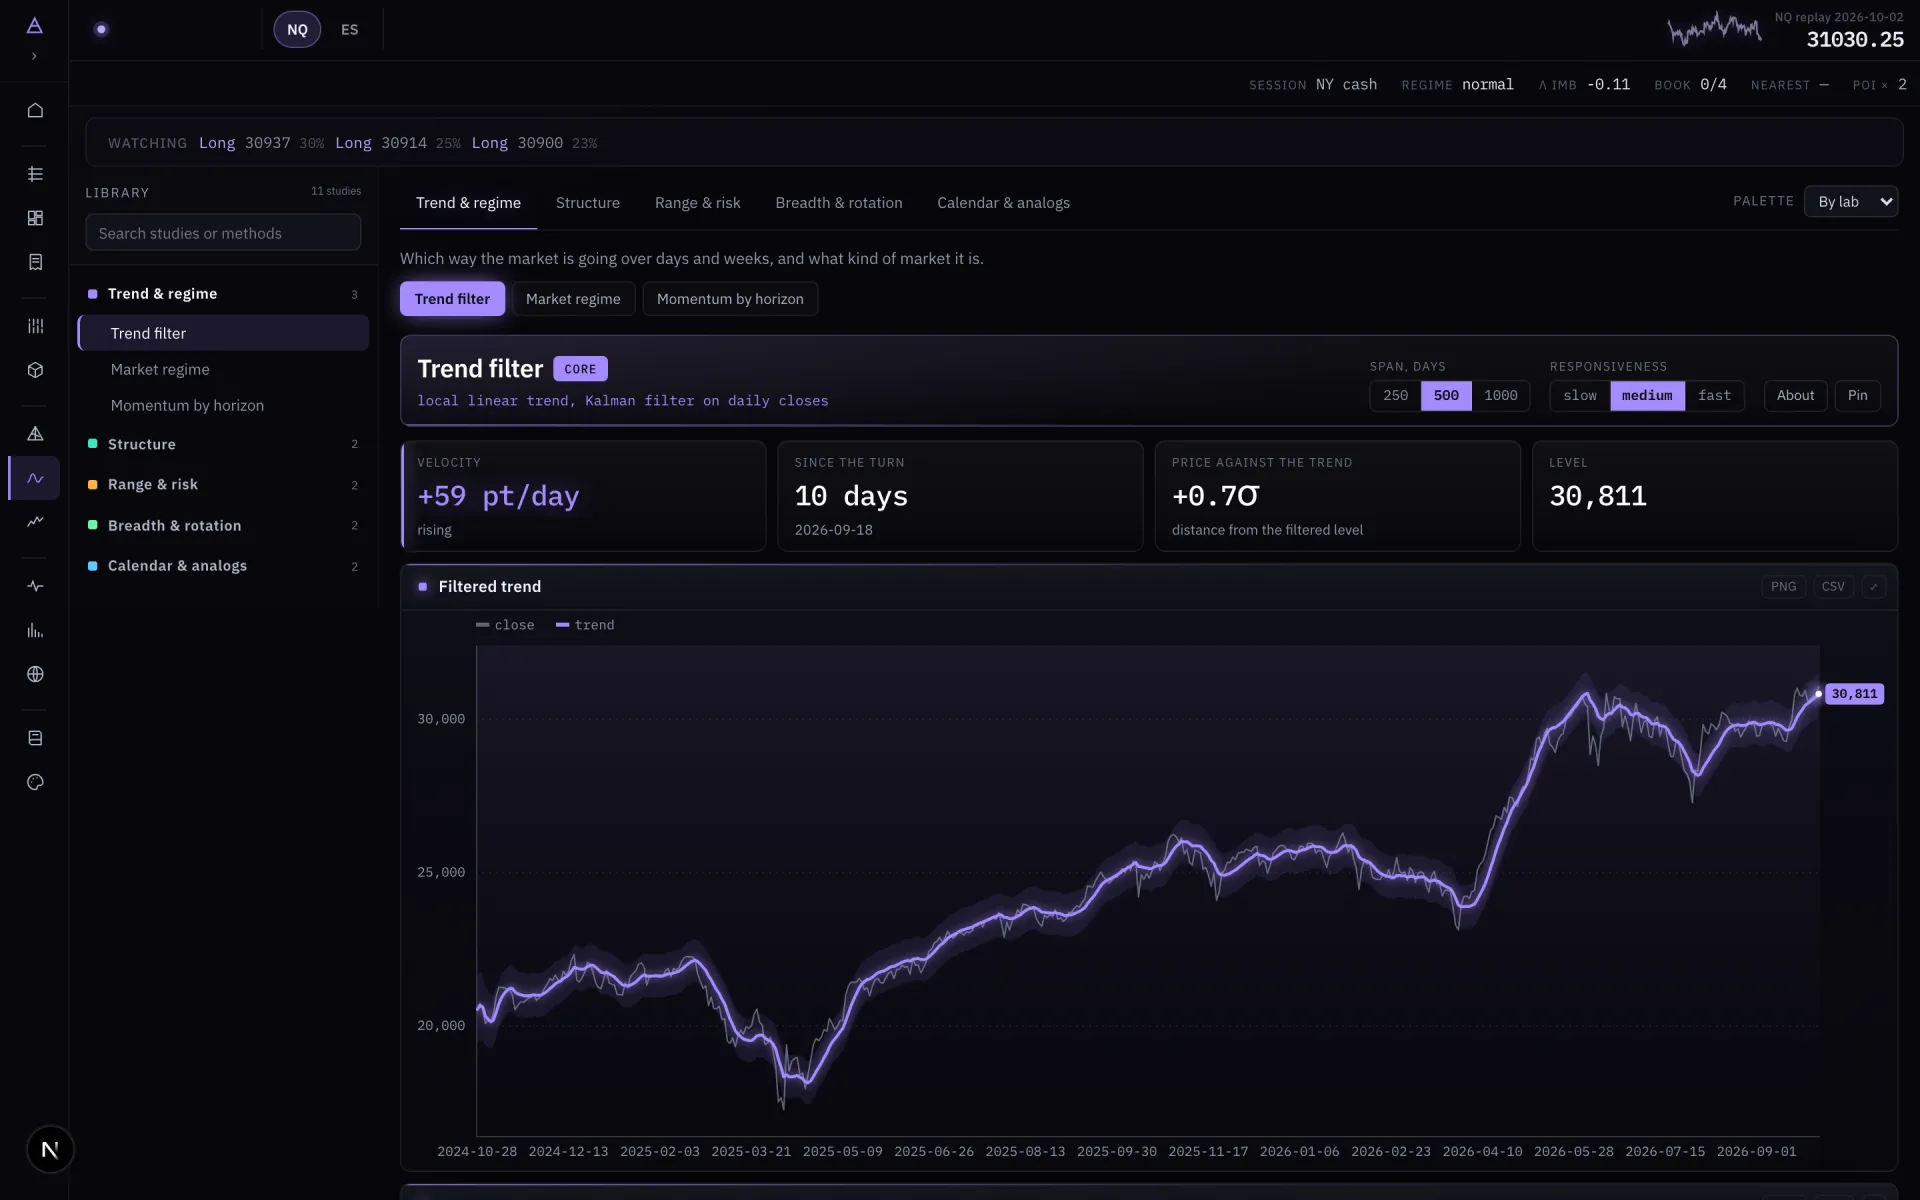
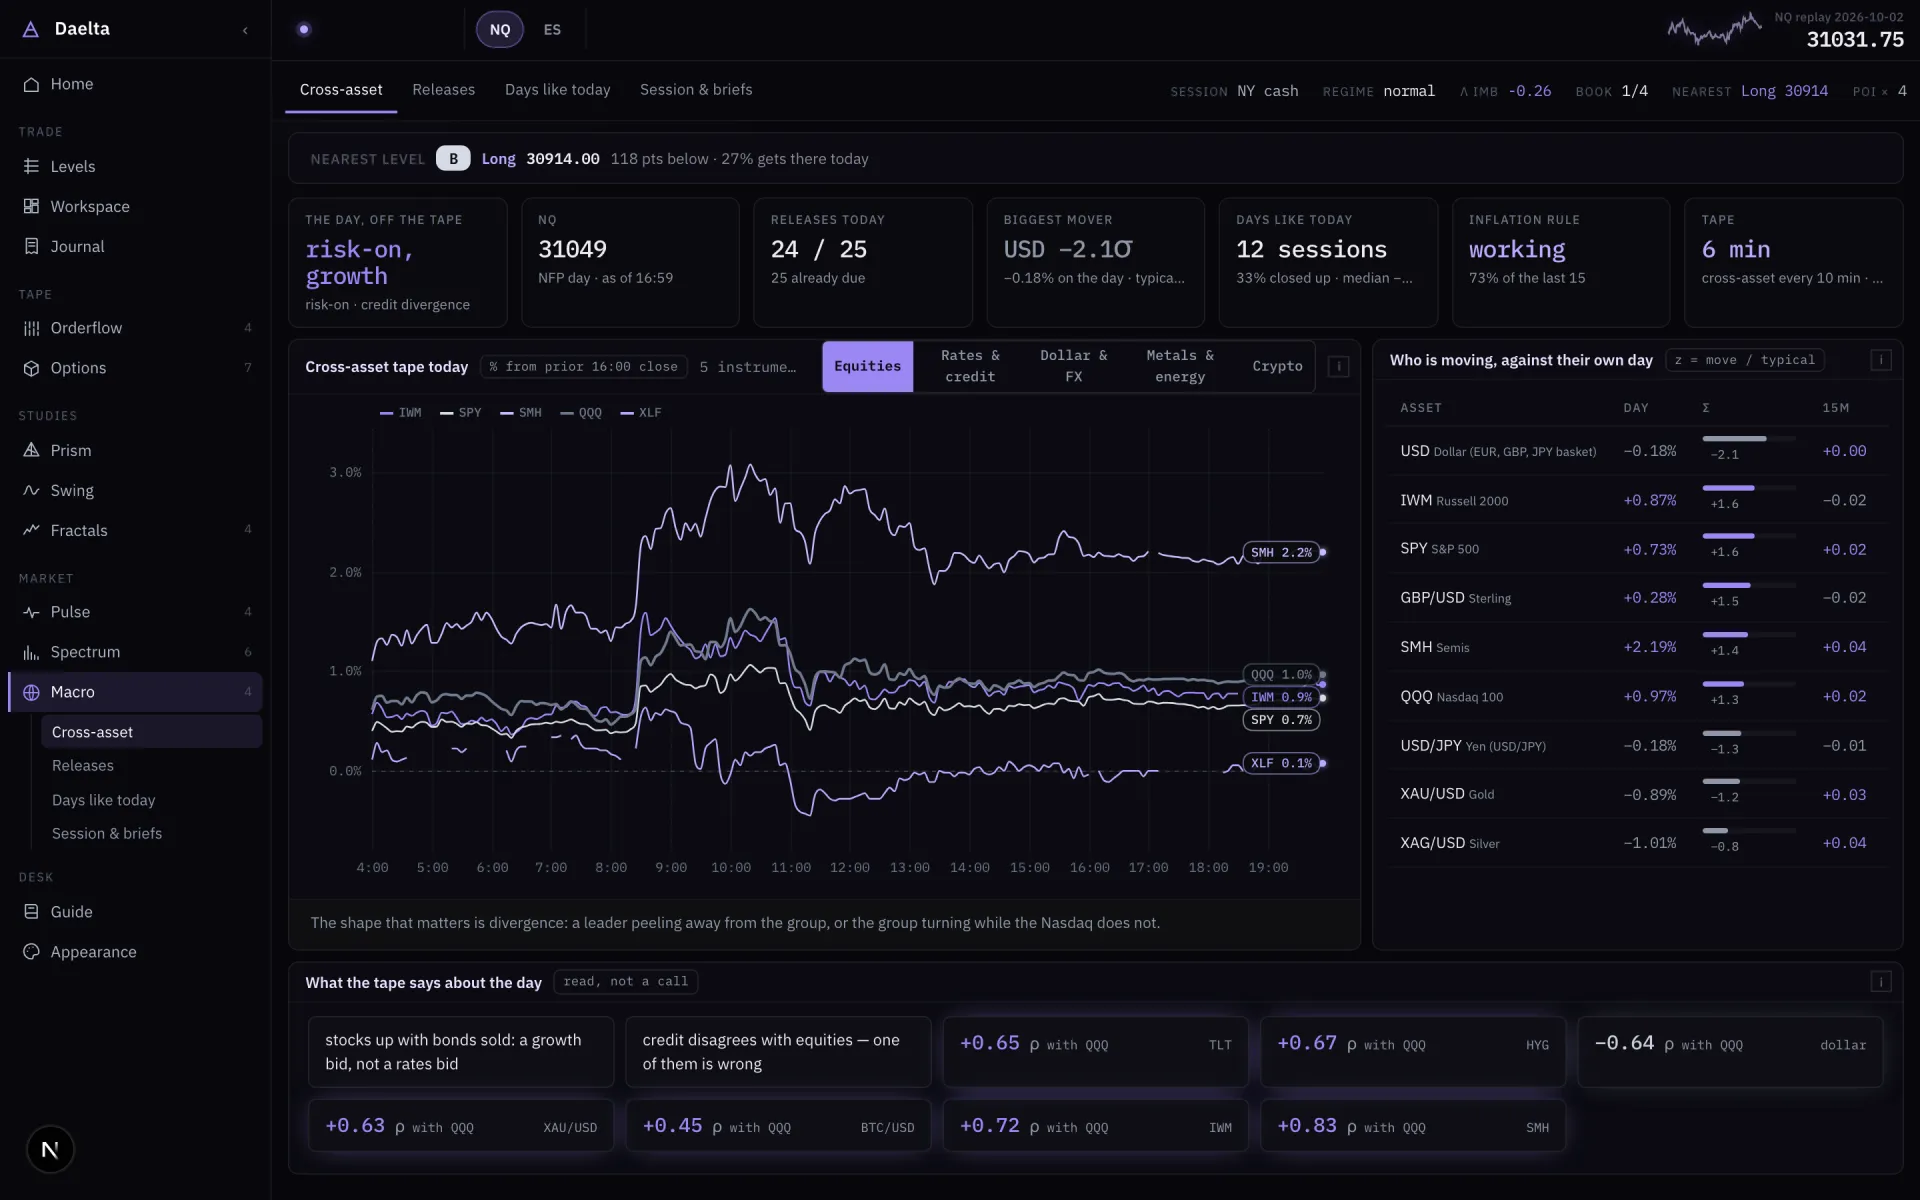
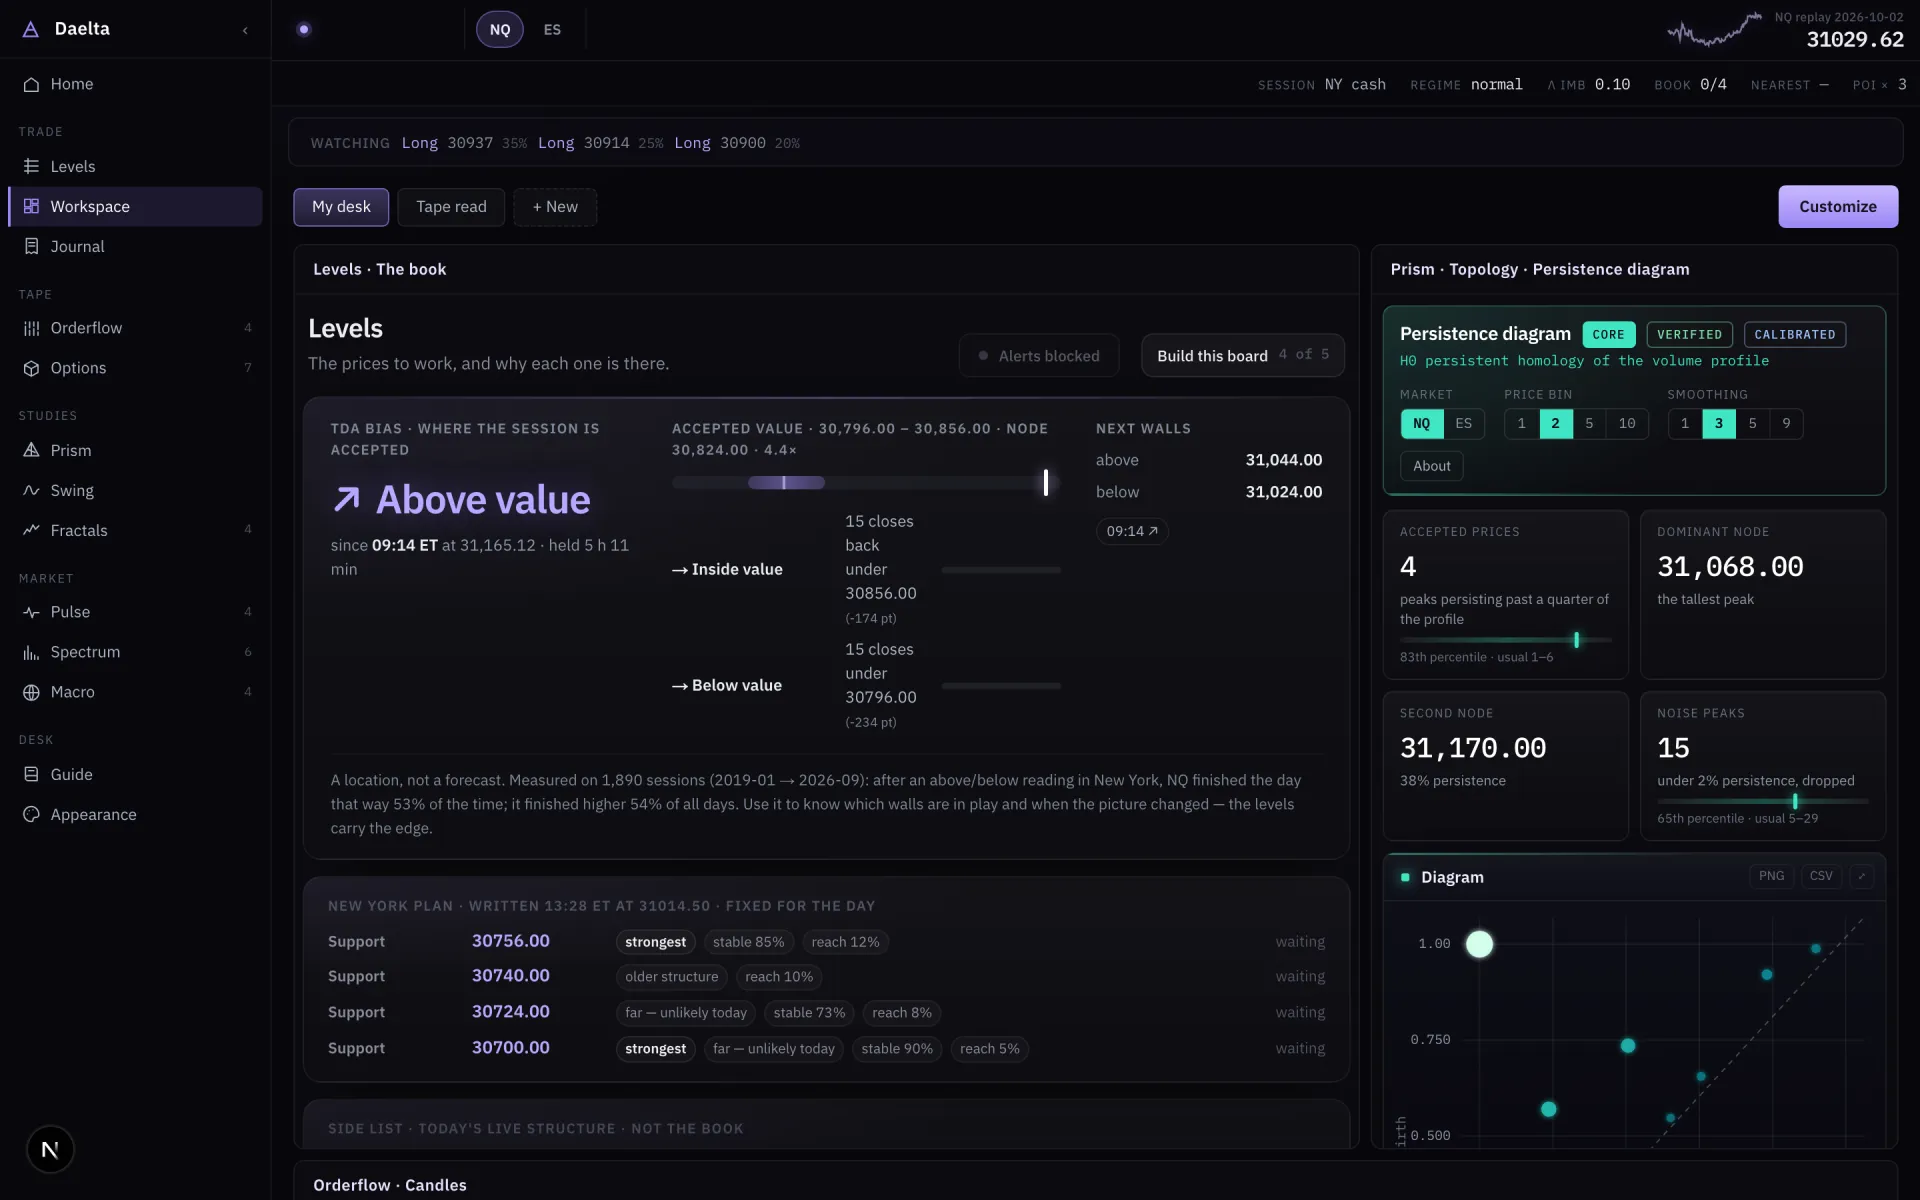
candles with the studies overlaidShannon entropy of the persistence diagram, through timeH0 persistent homology of the volume profileBubenik landscapes of the H0 diagramnumber of connected components by thresholdTakens delay embedding, H1 by Vietoris–RipsWasserstein distance between persistence diagramsMapper: cover by price, cluster by timecumulative volume at price through timeH0 persistence under increasing smoothingspectrogram of traded volume, ten-minute windowprint-size distribution and its power-law tailHawkes branching ratio and the memory kernel of arrivalscounts per second against a Poisson clockVPIN: volume-synchronized probability of informed tradingorder-flow imbalance regression (Cont, Kukanov, Stoikov)autocorrelation of trade signs (Lillo–Farmer long memory)traded volume by hour and minutenet delta as a share of volume, half-hour bucketsreturns under time, volume and trade clocks (Clark; Ané & Geman)volume by the last digits of the priceseconds far above the local arrival rate, groupedParkinson, Garman–Klass, Rogers–Satchell against realizedcross-correlation of returns with later squared returnsrealized variance, bipower variation, Lee–Mykland jumpsrealized volatility by sampling intervalabsolute return by time of day, session by sessionHAR-RV (Corsi): daily, weekly and monthly componentsscaling of log-volatility increments (Gatheral, Jaisson, Rosenbaum)distribution of realized volatility by horizonrolling volatility of volatility, realized skewness and kurtosisGARCH(1,1) fitted by maximum likelihoodrealized semivariance and signed jump variationWald–Wolfowitz runs test, streak-length distributionBayesian online change-point detection (Adams & MacKay)Gaussian hidden Markov model, Baum–Welchtwo-sided cumulative sum of standardized returnscontinuous wavelet transform, MorletWelch periodogram of one-second returnsfirst-order Markov chain on direction × volatilityLo–MacKinlay variance-ratio profileempirical first-passage frequencies from the tick archiveOrnstein–Uhlenbeck fit of price minus VWAPlocal linear trend state-space model, Kalman filterreflection principle for driftless Brownian motionStudent-t fit by maximum likelihood, QQ plotDFA: scaling of the detrended walkstationary block bootstrap of the session's returnsscaling of the mean absolute increment over a rolling windowbootstrap particle filter, stochastic-volatility modelMarchenko–Pastur law (random-matrix theory)
candles with the studies overlaidShannon entropy of the persistence diagram, through timeH0 persistent homology of the volume profileBubenik landscapes of the H0 diagramnumber of connected components by thresholdTakens delay embedding, H1 by Vietoris–RipsWasserstein distance between persistence diagramsMapper: cover by price, cluster by timecumulative volume at price through timeH0 persistence under increasing smoothingspectrogram of traded volume, ten-minute windowprint-size distribution and its power-law tailHawkes branching ratio and the memory kernel of arrivalscounts per second against a Poisson clockVPIN: volume-synchronized probability of informed tradingorder-flow imbalance regression (Cont, Kukanov, Stoikov)autocorrelation of trade signs (Lillo–Farmer long memory)traded volume by hour and minutenet delta as a share of volume, half-hour bucketsreturns under time, volume and trade clocks (Clark; Ané & Geman)volume by the last digits of the priceseconds far above the local arrival rate, groupedParkinson, Garman–Klass, Rogers–Satchell against realizedcross-correlation of returns with later squared returnsrealized variance, bipower variation, Lee–Mykland jumpsrealized volatility by sampling intervalabsolute return by time of day, session by sessionHAR-RV (Corsi): daily, weekly and monthly componentsscaling of log-volatility increments (Gatheral, Jaisson, Rosenbaum)distribution of realized volatility by horizonrolling volatility of volatility, realized skewness and kurtosisGARCH(1,1) fitted by maximum likelihoodrealized semivariance and signed jump variationWald–Wolfowitz runs test, streak-length distributionBayesian online change-point detection (Adams & MacKay)Gaussian hidden Markov model, Baum–Welchtwo-sided cumulative sum of standardized returnscontinuous wavelet transform, MorletWelch periodogram of one-second returnsfirst-order Markov chain on direction × volatilityLo–MacKinlay variance-ratio profileempirical first-passage frequencies from the tick archiveOrnstein–Uhlenbeck fit of price minus VWAPlocal linear trend state-space model, Kalman filterreflection principle for driftless Brownian motionStudent-t fit by maximum likelihood, QQ plotDFA: scaling of the detrended walkstationary block bootstrap of the session's returnsscaling of the mean absolute increment over a rolling windowbootstrap particle filter, stochastic-volatility modelMarchenko–Pastur law (random-matrix theory)
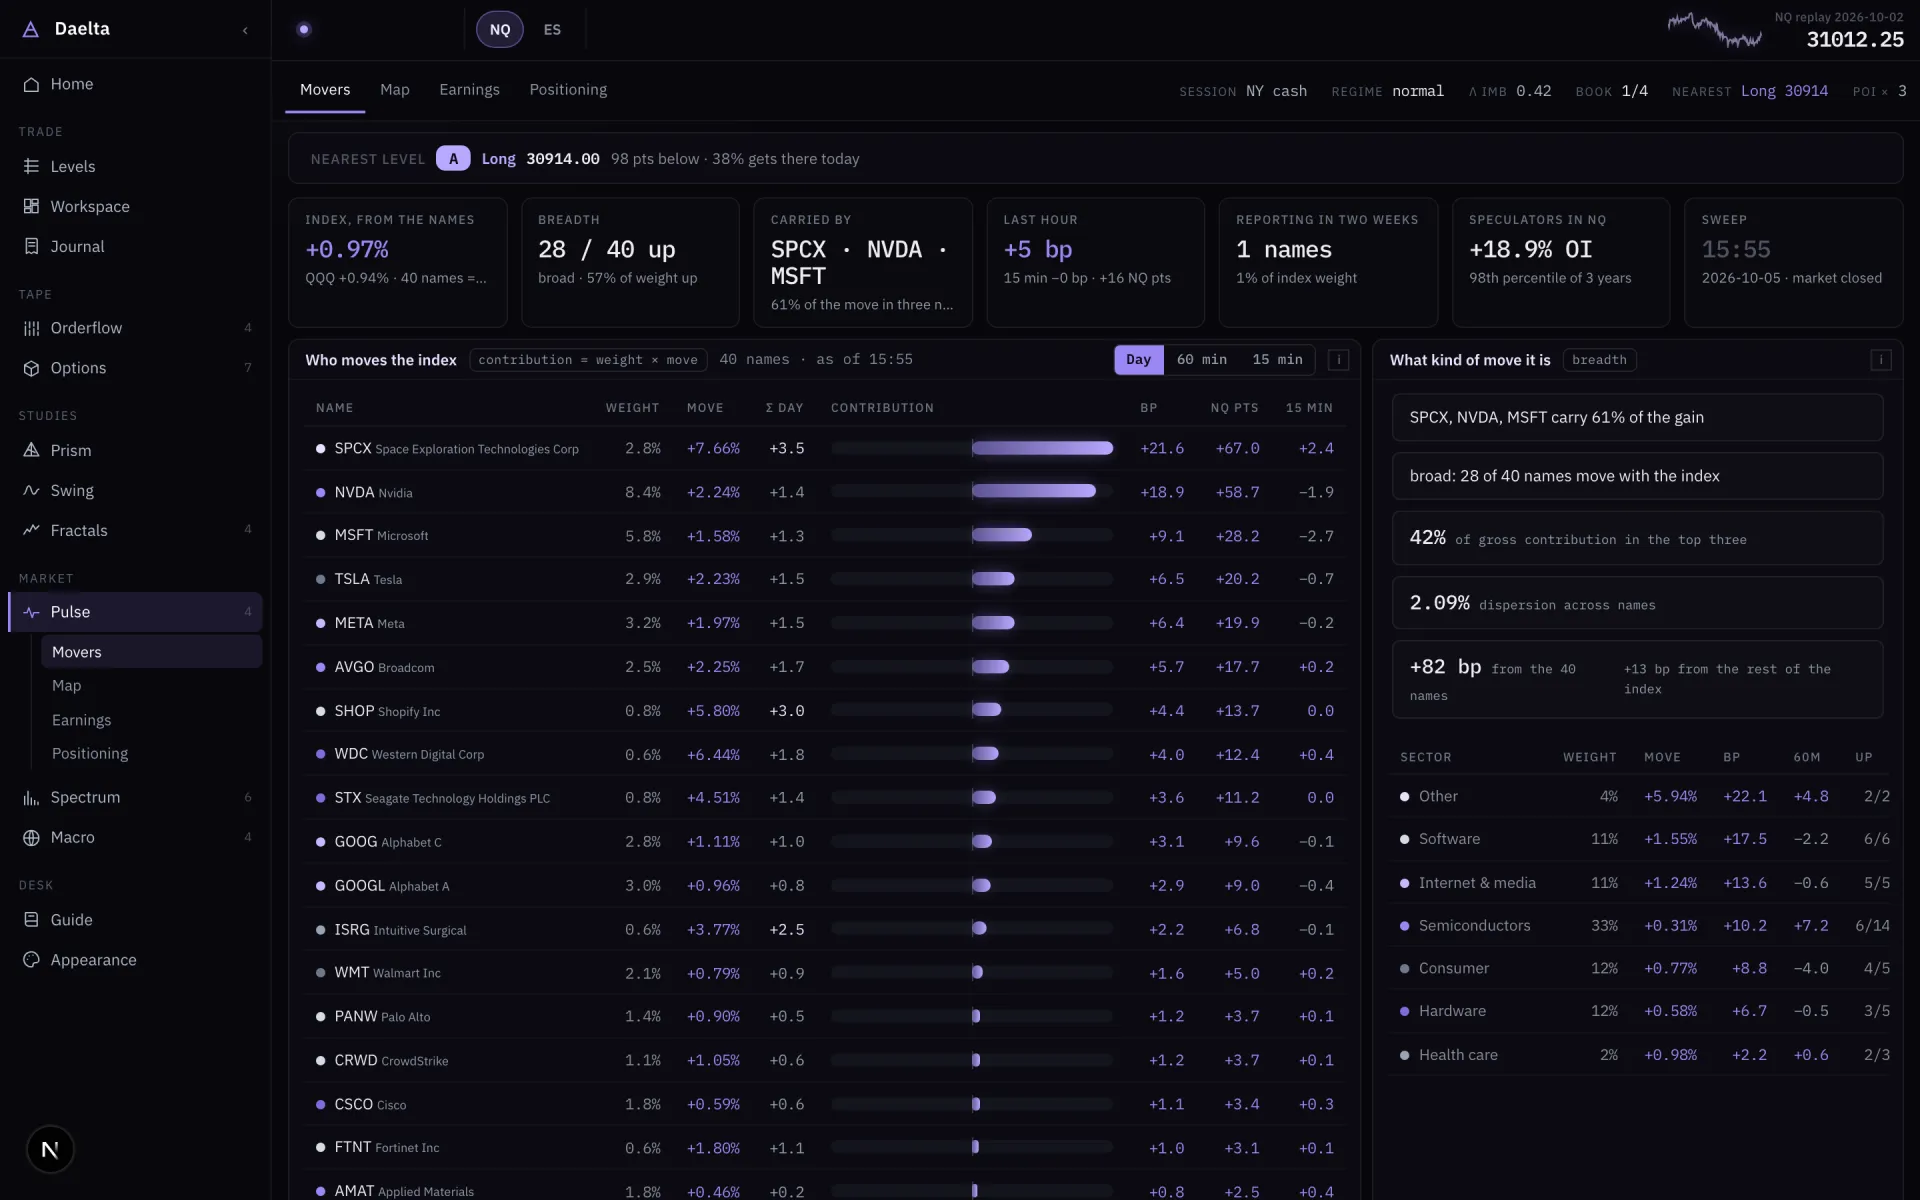
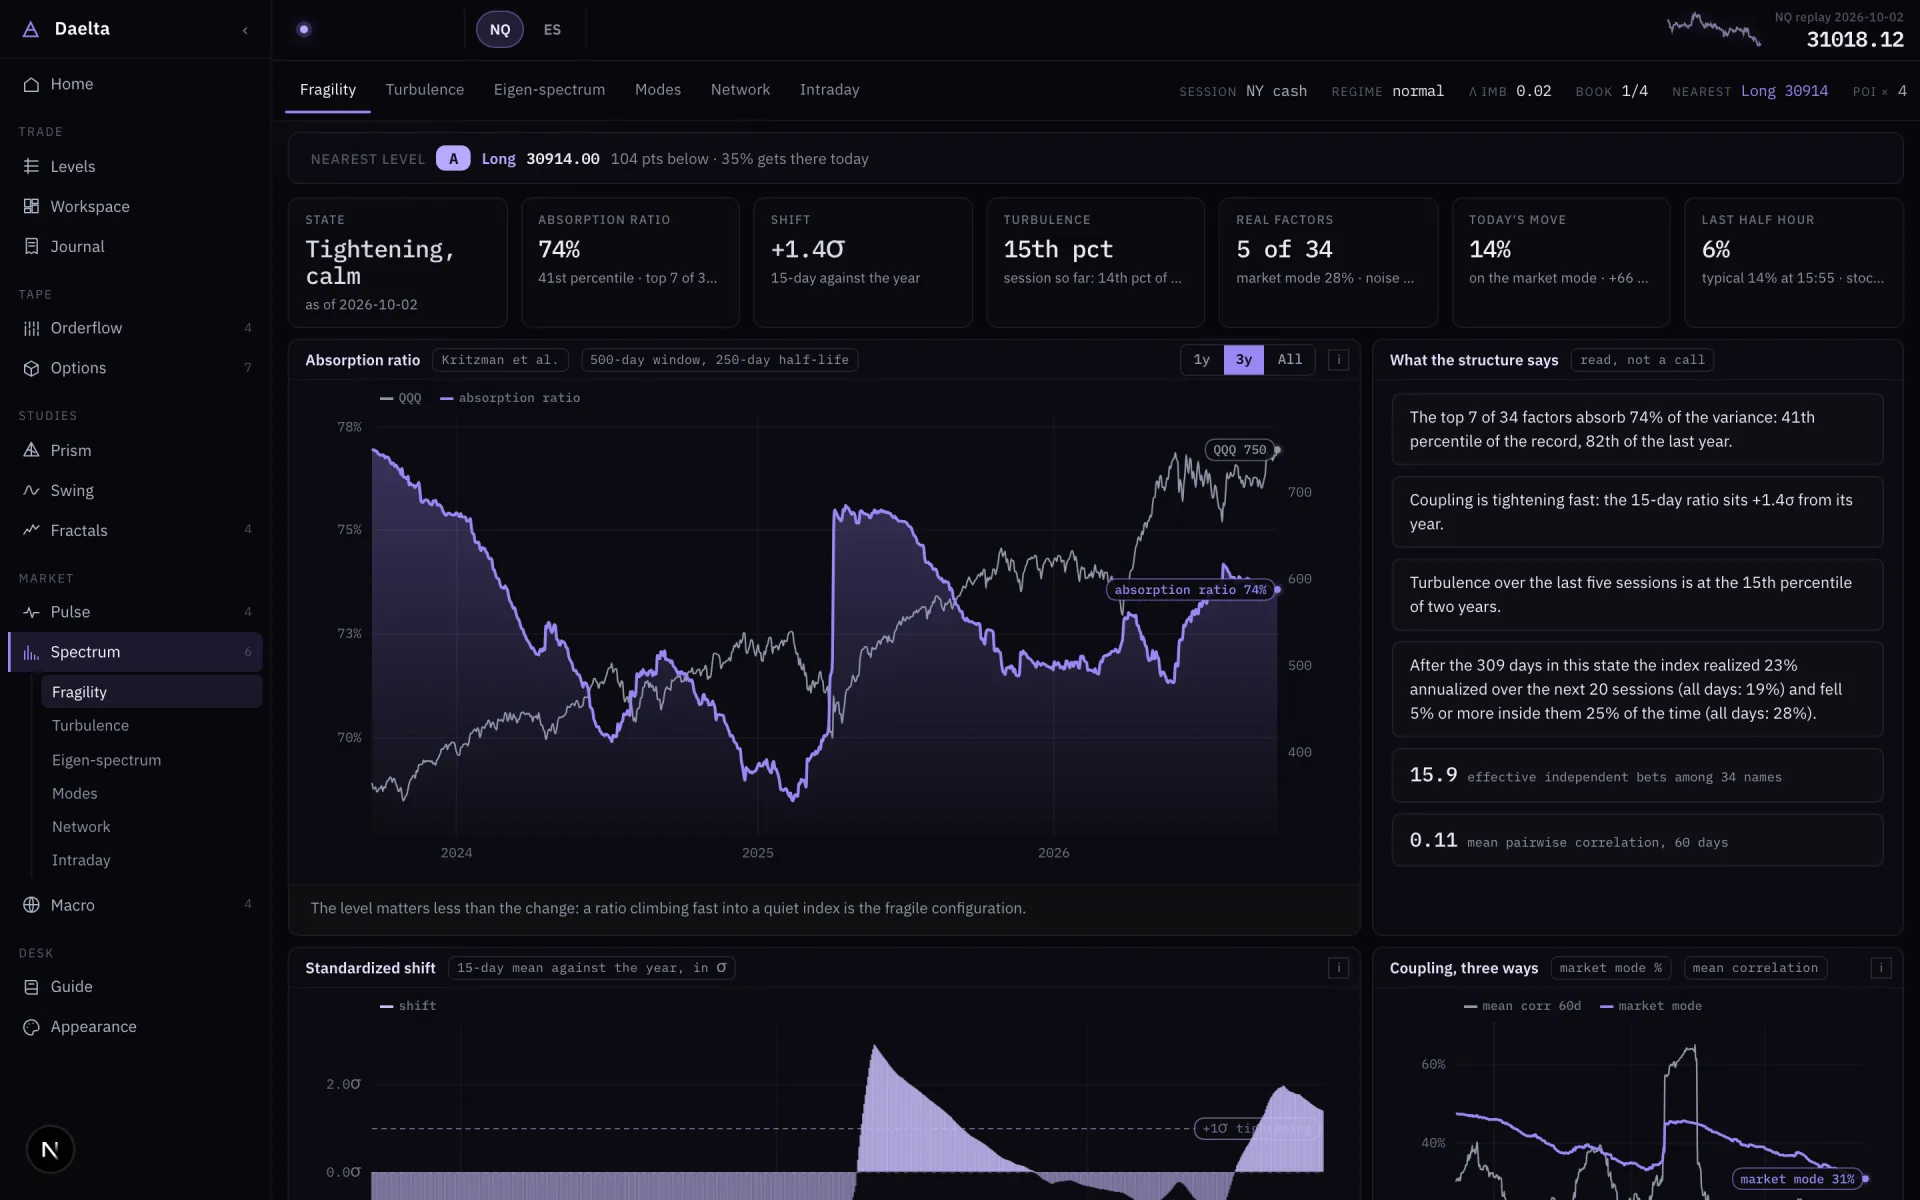
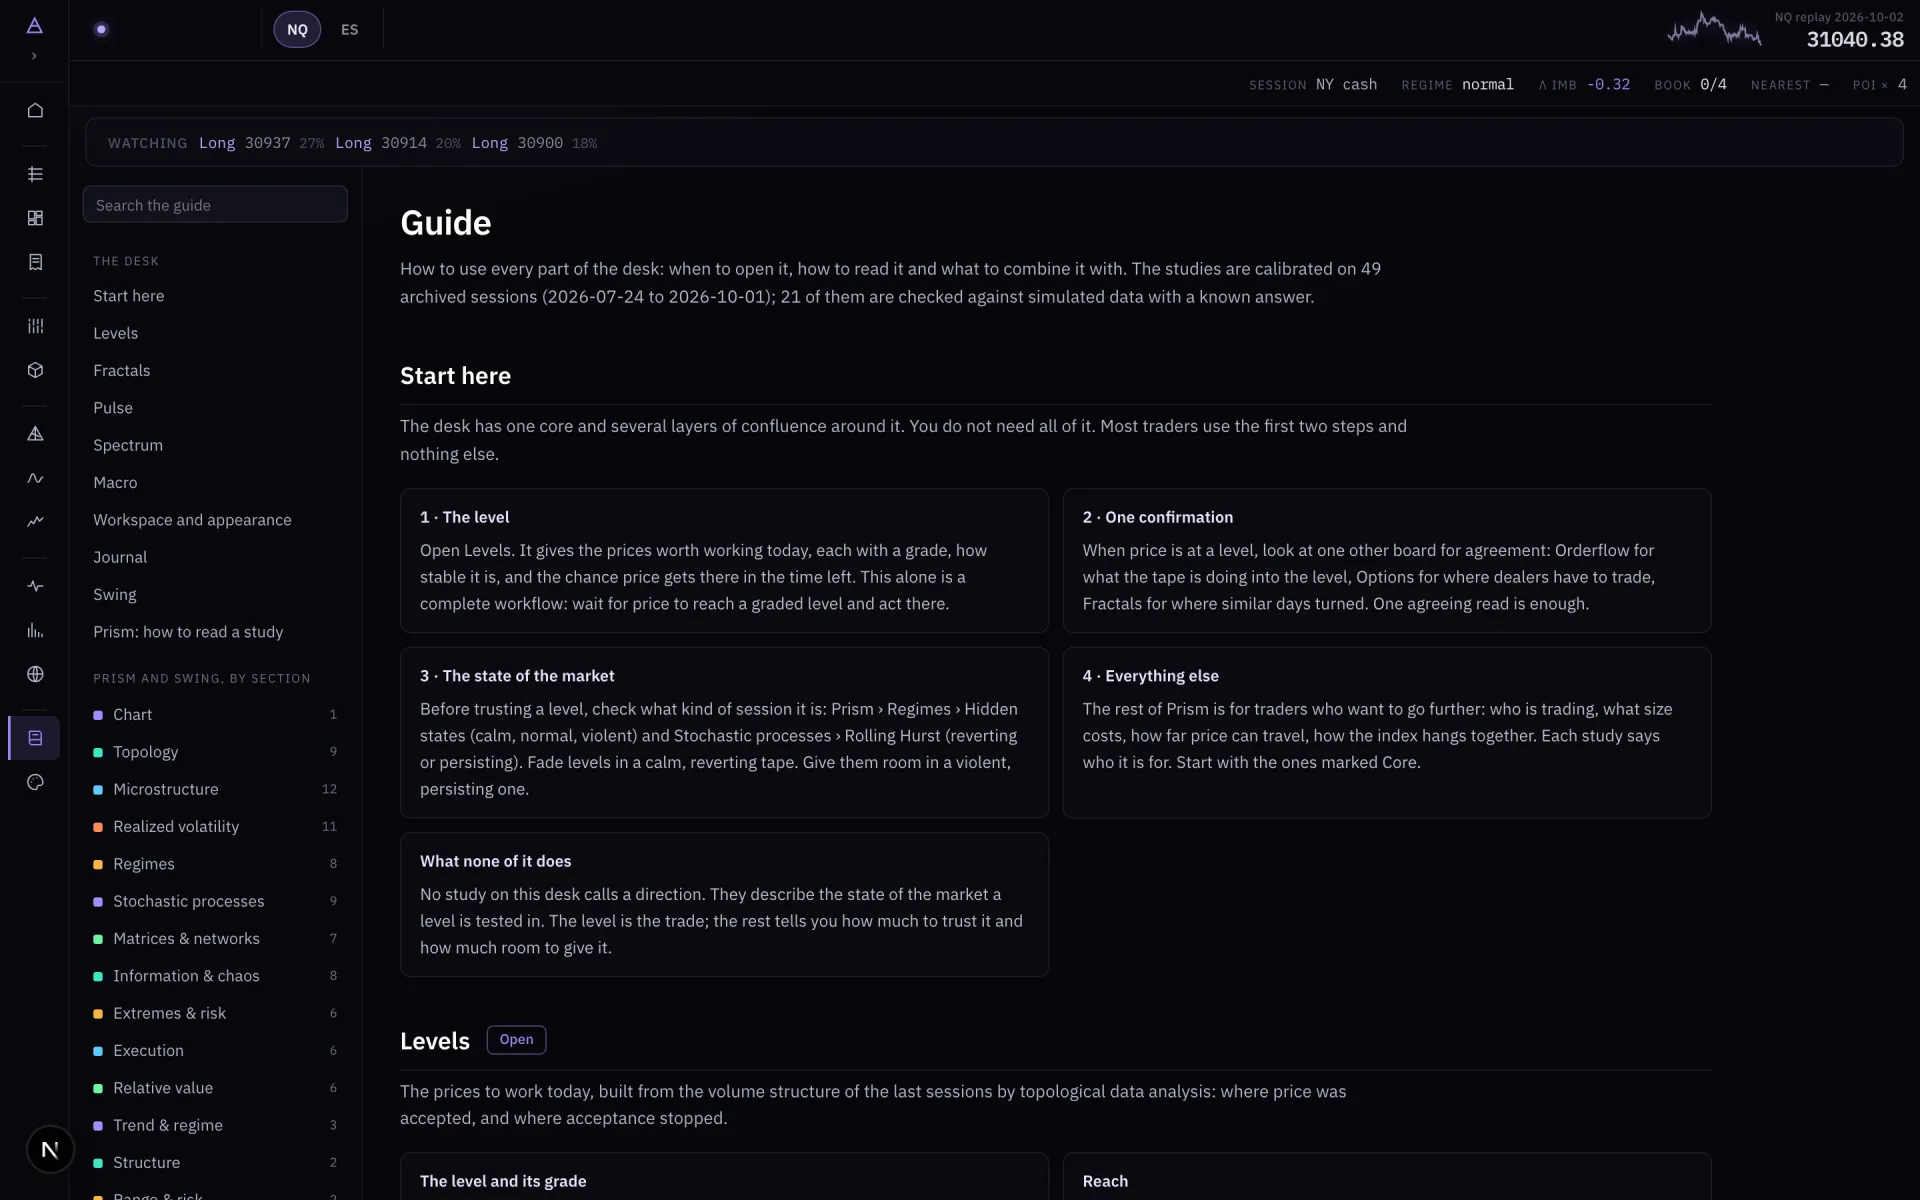
raw, RMT-cleaned and residual correlation, clusteredminimum spanning tree of the correlation distanceKritzman et al.: variance absorbed by the top eigenvectorseigenvector centrality of the cleaned correlation networkprojection of today's returns on the eigenvectorsstandard deviation of the names' returns, day by daypermutation entropy at several orders, spectral entropyrecurrence quantification of the embedded pathlargest Lyapunov exponent (Rosenstein)structure functions and the Legendre transformauto mutual information against linear autocorrelationjoint density of consecutive returnsGrassberger–ProcacciaLZ76 complexity of the up/down sequenceHill tail index on each side of the recordpeaks over threshold, generalized Pareto, Hill estimatorhistorical VaR and expected shortfall by horizonintraday maximum drawdown and run-up over the recordquantiles of the maximum adverse move by holding periodquantile fan of cumulative range by time of daysquare-root impact lawAlmgren–Chriss efficient frontiertraded volume by time of day, session by sessionRoll effective spread, Amihud illiquidity, Kyle's lambdavolume curve and participation schedulesquare-root impact by time of dayGranger causality on five-second returnscross-correlation of one-second returnsKalman-filtered regression of returnsEngle–Granger: regression, Dickey–Fuller on the residualempirical copula of one-minute returnsrolling correlation and beta at several windowsCUSUM on the minute-by-minute imbalance of sized prints; bumps in the gap distribution of same-size trainsthe sized prints of each detected program, drawn on the price pathrule-based classes of prints, by minutesame-side prints clearing three or more prices inside sixty milliseconds; single prints of forty lots or moreprices refilled from icebergs on the live book; absorbed volume against displayed size in the order-book archivelinear quantile regression on realized variance and volume, walk-forward on the archivespread and depth from the quote feed; impact from the one-second tapeVWAP, TWAP, POV and Almgren–Chriss schedules from here to the closelocal linear trend, Kalman filter on daily closesGaussian hidden Markov model on daily returnstrailing returns in units of their own history, variance ratiosvolume at price over many sessions, H0 persistencedirectional-change legs on daily closesempirical k-day returns, scaled to current volatilityunderwater curve and drawdown episodesshare of index names above their moving averagesrelative strength against its own momentummean return by weekday and part of the month, with t-statisticsnearest past windows by the shape of the path
raw, RMT-cleaned and residual correlation, clusteredminimum spanning tree of the correlation distanceKritzman et al.: variance absorbed by the top eigenvectorseigenvector centrality of the cleaned correlation networkprojection of today's returns on the eigenvectorsstandard deviation of the names' returns, day by daypermutation entropy at several orders, spectral entropyrecurrence quantification of the embedded pathlargest Lyapunov exponent (Rosenstein)structure functions and the Legendre transformauto mutual information against linear autocorrelationjoint density of consecutive returnsGrassberger–ProcacciaLZ76 complexity of the up/down sequenceHill tail index on each side of the recordpeaks over threshold, generalized Pareto, Hill estimatorhistorical VaR and expected shortfall by horizonintraday maximum drawdown and run-up over the recordquantiles of the maximum adverse move by holding periodquantile fan of cumulative range by time of daysquare-root impact lawAlmgren–Chriss efficient frontiertraded volume by time of day, session by sessionRoll effective spread, Amihud illiquidity, Kyle's lambdavolume curve and participation schedulesquare-root impact by time of dayGranger causality on five-second returnscross-correlation of one-second returnsKalman-filtered regression of returnsEngle–Granger: regression, Dickey–Fuller on the residualempirical copula of one-minute returnsrolling correlation and beta at several windowsCUSUM on the minute-by-minute imbalance of sized prints; bumps in the gap distribution of same-size trainsthe sized prints of each detected program, drawn on the price pathrule-based classes of prints, by minutesame-side prints clearing three or more prices inside sixty milliseconds; single prints of forty lots or moreprices refilled from icebergs on the live book; absorbed volume against displayed size in the order-book archivelinear quantile regression on realized variance and volume, walk-forward on the archivespread and depth from the quote feed; impact from the one-second tapeVWAP, TWAP, POV and Almgren–Chriss schedules from here to the closelocal linear trend, Kalman filter on daily closesGaussian hidden Markov model on daily returnstrailing returns in units of their own history, variance ratiosvolume at price over many sessions, H0 persistencedirectional-change legs on daily closesempirical k-day returns, scaled to current volatilityunderwater curve and drawdown episodesshare of index names above their moving averagesrelative strength against its own momentummean return by weekday and part of the month, with t-statisticsnearest past windows by the shape of the path